All Categories
Featured
That's why 90%of leading worldwide financial investment banks take advantage of AlphaSense to appear the intelligence and insights teams trust to make their most important choices. While M&A activity in the insurance coverage sector has actually been more soft, strategic and monetary buyer appetite is still present. The primary themes affecting dealmaking consist of regional divergence; continued personal capital interest; broker debt consolidation going into a more mature stage; and structural shifts in capital, threat, and technology. Cross-border activity stays a vital part of the market, especially where purchasers are seeking diversity, specialty underwriting abilities, and access to attractive platforms. Nevertheless, raised geopolitical unpredictability, softening premium rates in some lines, inflation, and rates of interest volatility are leading buyers to be more disciplined when examining deals. Specialized home and casualty and Lloyd's platforms are anticipated to stay at the centre of tactical M&A. Current UK transactions and listed valuations reveal an appetite for services with strong underwriting returns, separated data, scalable distribution, and access to expert skill. Personal capital release into Lloyd's remains active, with financiers progressively concentrated on technology-enabled organizations, improved underwriting capabilities, and fee-based models. Additionally, rising levels of personal capital were released into Lloyd's through the London Bridge 2 structure in 20252026, which is anticipated to continue into 2027 . Insurance coverage circulation M&A is anticipated to continue, however the geographic focus is shifting. In Europe, activity is anticipated to moderate in the UK while speeding up across continental markets, with a particular concentrate on Germany, Austria, and Switzerland where fragmentation and private equity-backed consolidators continue to mature. Purchasers will increasingly require to demonstrate post-deal integration, provider management, technology uplift, and organic development. Private equity exits will continue as earlier roll-up plays fully grown, but acquirers are ending up being more focused on combination, technology capabilities, and organic development in a softer rate environment. Managing basic representative( MGA) M&A has actually increased over the last few years with carriers, brokers, and financial sponsors all looking for opportunities. MGAs stay attractive due to the fact that of their increased market share, capital light organization model, and underwriting specialisation, frequently with the ability to make substantial revenue commission. MGAs with embedded
data and analytics and platform debt consolidation chances are expected to be significantly demanded assets. In life and annuities, personal capital and possession managers will continue to seek access to long period of time liabilities and fee income while insurance providers will seek origination capability and higher yielding assets. The Danish Compromise may likewise result in a brand-new swimming pool of interested buyers as European banks look to widen their abilities. Innovation will be more targeted than in previous cycles : acquirers will prioritise AI, analytics, and digital platforms that improve underwriting, pricing, claims, cyber strength, and entrusted authority oversight. As assessment discipline tightens, the very best targets will be those that combine specialty expertise, verifiable information advantages, and a practical path to integration.
Stakeholder Demands: Why Transparent ESG Reporting Is NecessaryThe unmatched public health, financial, and social effects of the global COVID-19(unique coronavirus)pandemic have actually magnified the forces that are creating difficulties and speeding up disturbance in the financial investment banking industry: falling equity prices, liquidity stress, progressing financial guidelines, market democratization, prices pressure, increased customer sophistication, moves to remote working arrangements, and rapid fast innovation. Market realignment ought to produce opportunities for financial investment banks to drive toward higher levels of return.
Top Strategic Priorities for UK Enterprises in 2026
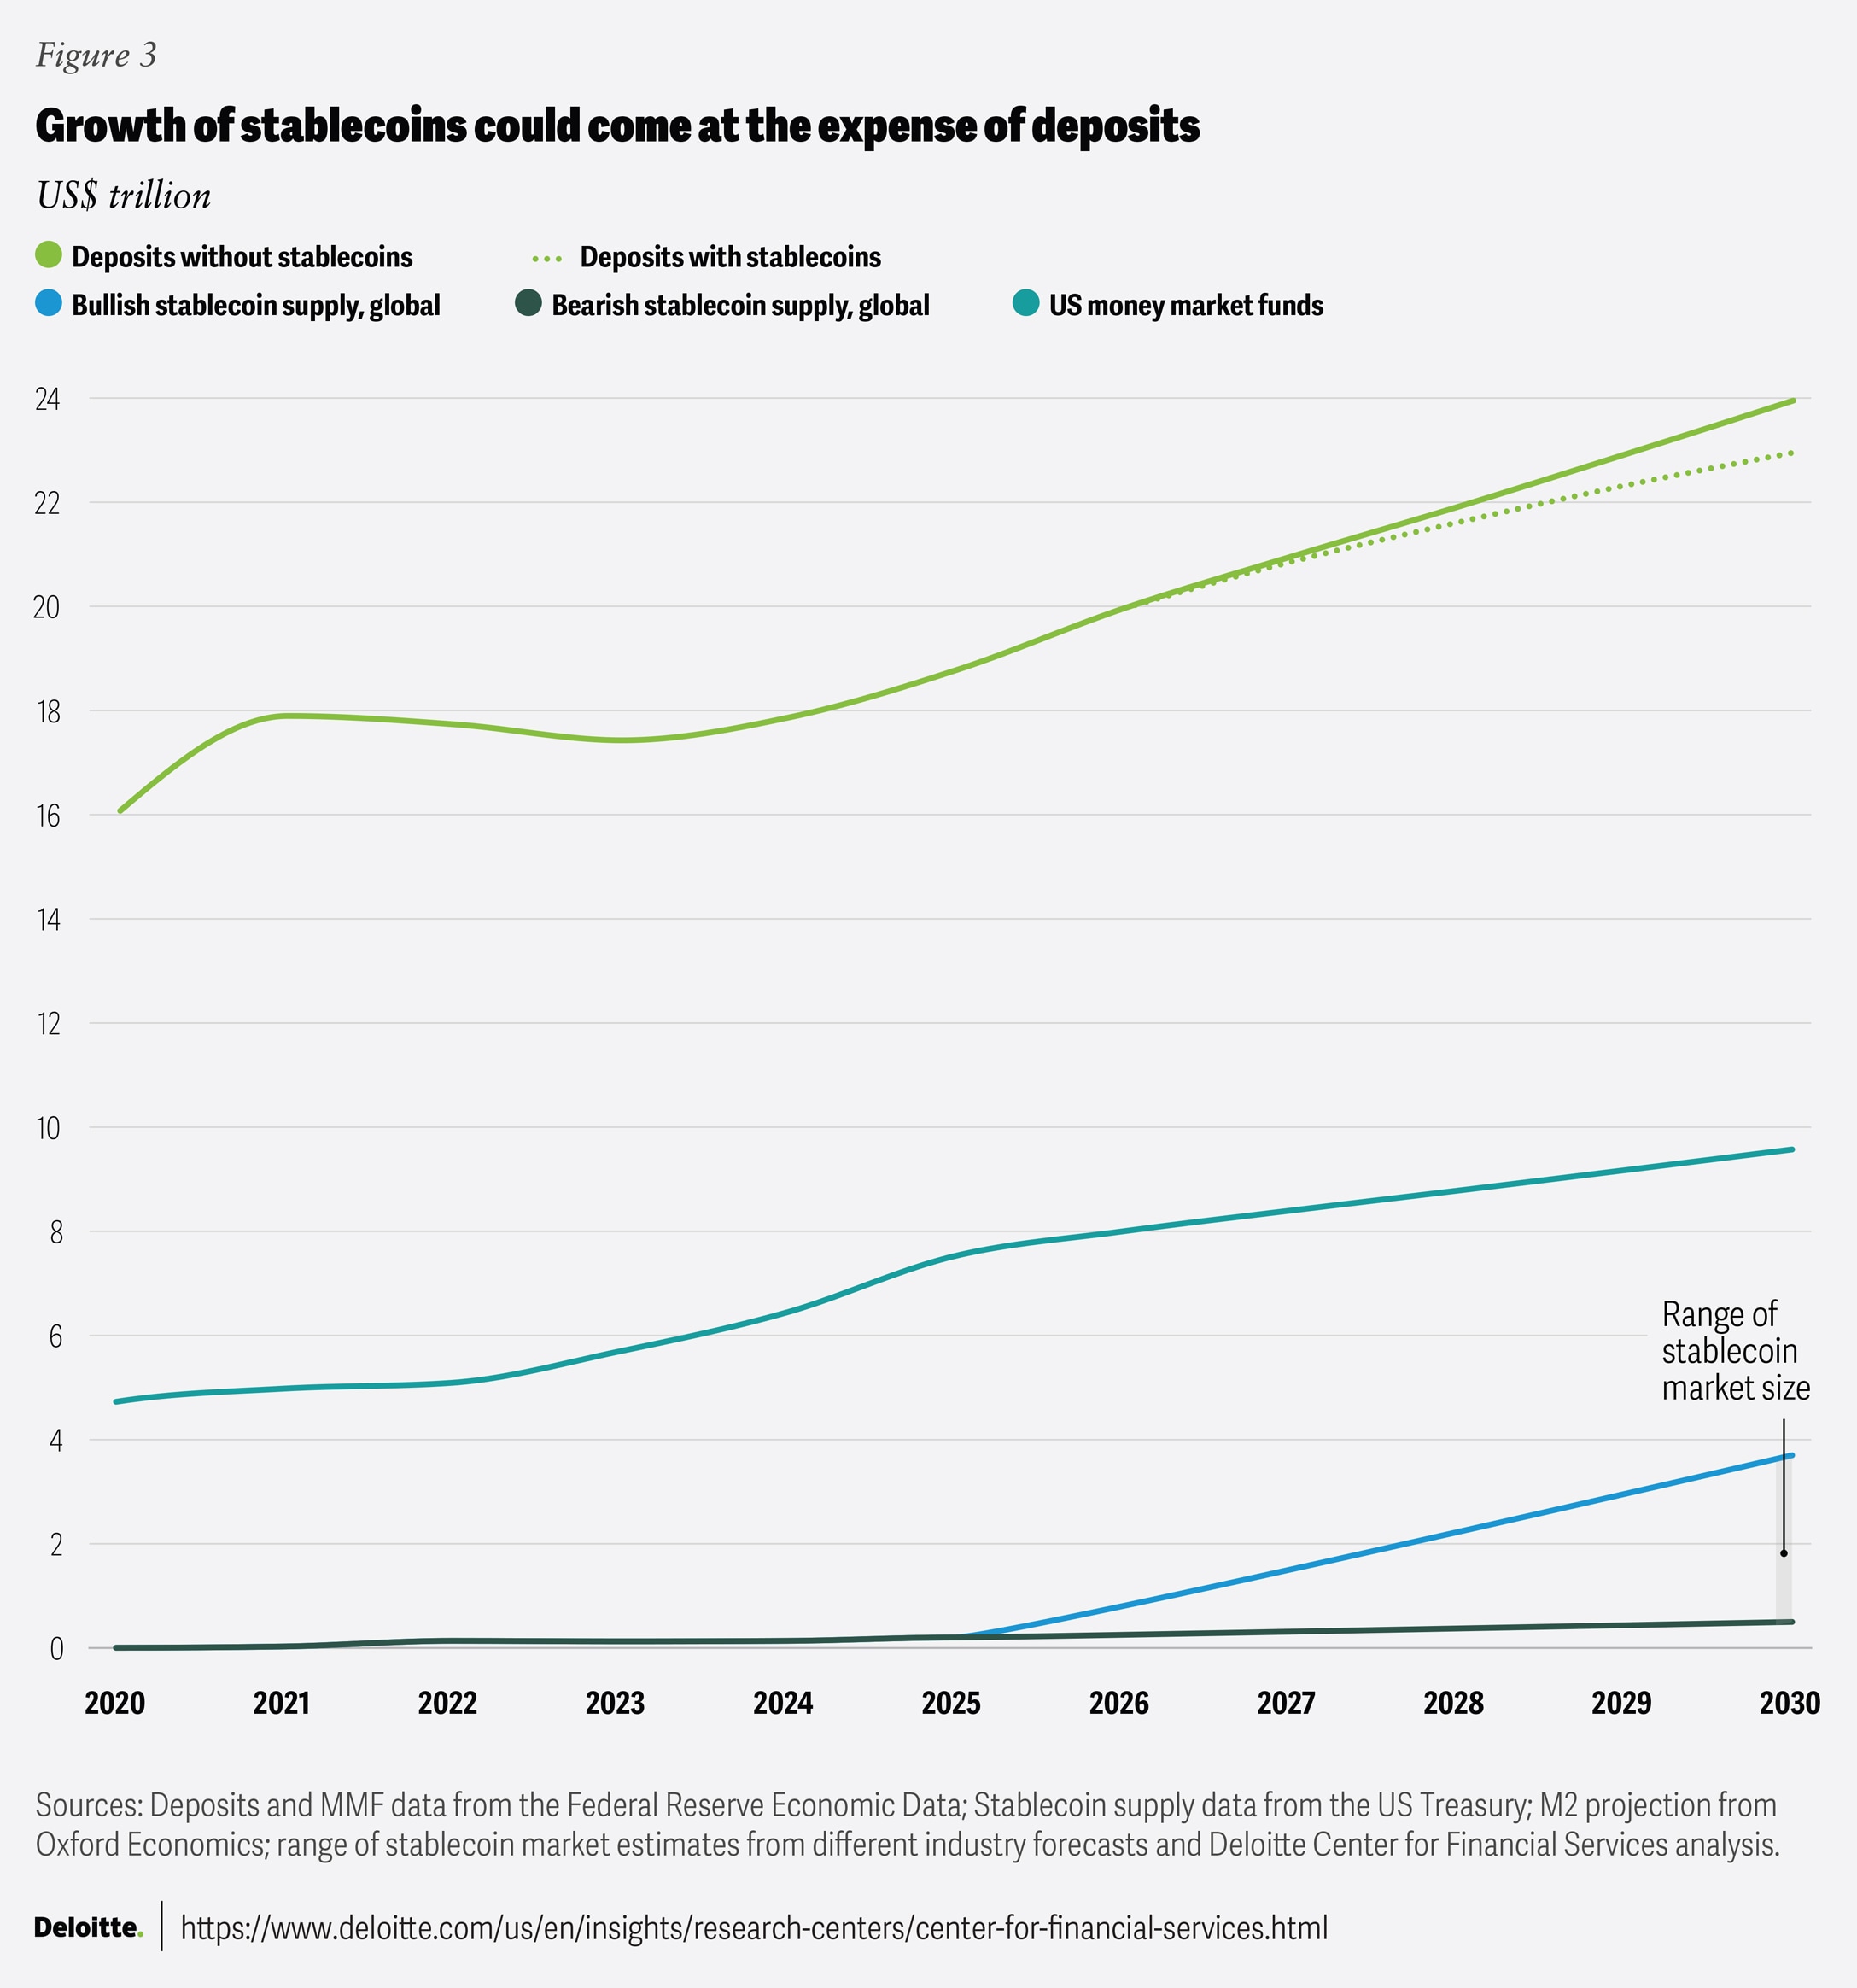
,"Deloitte Insights, Sept. 30, 2025., "Federal Reserve Bank of New York, accessed Sept. 8, 2025.,"The Wall Street Journal, Aug.
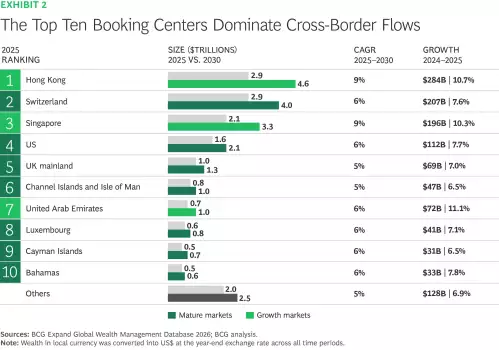
Saloni Goel, "European bank stocks surge to highest level since 2008 global monetary crisis.," Citi Institute, April 23, 2025; J.P. 4, 2025. Sergio Goschenko,"Stablecoin companies harness loopholes in the GENIUS Act to use'benefits'," News, Aug. 5, 2025.

Latest Posts
Why Digital Tools Scale for 2026 Mid-Market
Logistics Reports and UK Industry Growth
Sustainable Finance and Ethical Value Chains in 2026