All Categories
Featured
Table of Contents
The vacancy-to-unemployment ratio supplies a beneficial lens here (figure B). While the labour market has cooled significantly from the extraordinary tightness of 2021-22, jobs have actually more recently stabilised even as joblessness has continued to edge up. This pattern suggests that the change in the labour market is increasingly taking place through slower hiring and weaker task matching.
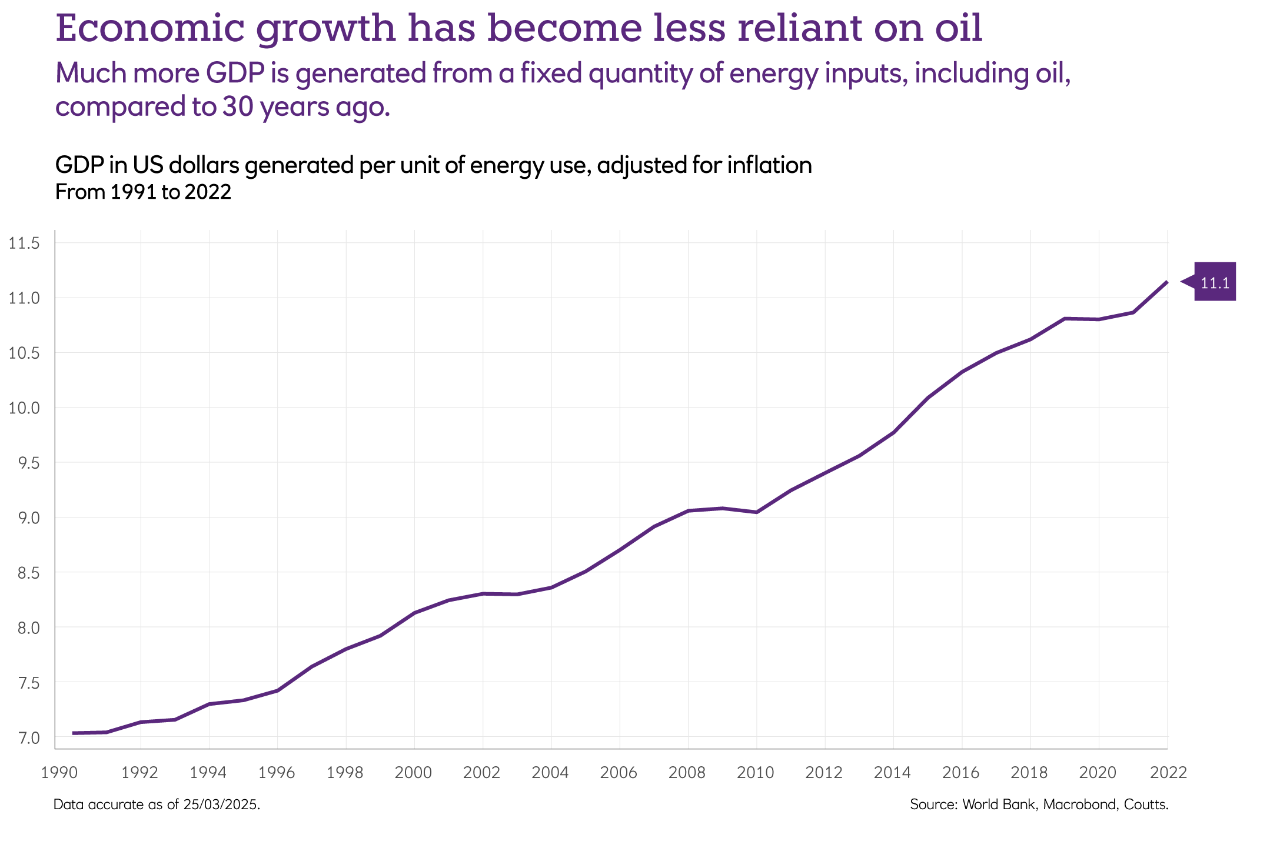
While our main forecast does not assume such a shift, this is an essential danger that we are monitoring closely. Evidence from service studies recommends AI is currently being used mainly to augment particular tasks especially in administrative, analytical and customer-facing functions instead of to drive large-scale labor force decreases. Reported performance gains have actually so far been concentrated in narrow functions, with limited immediate influence on overall employment.
For the Monetary Policy Committee, the key judgement is how quickly increasing unemployment equates into lower wage development and services inflation. While we anticipate Bank Rate to fall to 3.25 percent by year-end, consistent wage pressures provide a threat to this view. For the public finances, slower employment growth and weaker earnings dynamics would minimize earnings tax and National Insurance invoices.
The UK economy will grow more slowly next year than any other significant sophisticated nation as taxes and high interest rates take their toll, according to the most recent projections from the OECD. In a gloomy outlook, the Organisation for Economic Co-operation and Development reduced its forecast for UK growth from 0.7 percent to 0.4 percent, the most affordable in the G7 apart from Germany.
In 2025, it predicts that the UK will grow by 1 percent the weakest performance in the G7. By contrast, the US economy is predicted to power ahead this year with 2.6 per cent growth, followed by Canada at 1 percent, and Italy and France at 0.7 percent.
Securing Venture Capital for British Financial Markets
German financial development is forecast to increase from 0.2 percent this year to 1.1 percent next year, which will see it leapfrog Britain. The OECD outlook is more pessimistic than that issued by the International Monetary Fund (IMF) previously this year, which anticipate UK development of 1.5 per cent.
Interest rates required to remain high in order to deal with sticky inflation, it stated. "The fiscal and financial policy mix is sufficiently restrictive and ought to remain so up until inflation returns durably to target (2%)," the OECD's UK financial outlook for 2024 discovered.
Ethical Mandates and Sustainable Banking ModelsThe OECD expects eurozone inflation currently 2.4 percent will be considerably lower than UK inflation currently 3.2 per cent over the same duration. The think tank said "financial vigilance" is required till the Bank of England's inflation target of 2 percent is satisfied, and that federal government spending ought to be directed towards "supply-enhancing financial investment" such as the NHS.
Ensuring Sustainable Value Networks Via Strategic Alignment
The unemployment rate increased to 4.2 percent for the most recent three-month period to February. The OECD forecasts this will continue to increase, reaching as high as 4.7 percent in 2025 "as the labour market cools". Chancellor Jeremy Hunt said the OECD forecast was unsurprising given "our concern for the last year has been to take on inflation with greater rate of interest.
Get latest updates and insights provided to your inbox.
[LONDON] The International Monetary Fund raised its growth forecast for Britain's economy this year on Monday (May 18) however warned that more "domestic uncertainty", at a time when political instability is swallowing up the government, could hit spending and financial investment. In an upgrade that financing minister Rachel Reeves hailed as a sign of progress by embattled Prime Minister Keir Starmer's government, the IMF stated Britain's economy would grow by 1.0 percent this year.
However it would still represent a downturn for Britain from 2025." While the UK economy has remained resilient in the last few years, the war in the Middle East is dampening near-term potential customers," the IMF stated in its yearly assessment of Britain's economy. The new, greater forecast for 2026 was due to pre-war economic momentum which was reflected in recent stronger-than-expected growth and modifications to previous information, the Fund stated.
Key Enterprise Strategies for UK Mid-Market Leaders
However, provided the unpredictability about the Iran conflict, the BOE might have to cut or raise rates and need to "be prepared to respond powerfully" if second-round results such as worker needs for greater pay or business raising their selling costs proved more powerful than prepared for. Over the past 2 weeks, British politics has been rocked by speculation about Starmer's future, driving benchmark 10-year borrowing costs to their highest given that 2008 on Friday on the prospect of weaker fiscal discipline.

Latest Posts
Why Digital Tools Scale for 2026 Mid-Market
Logistics Reports and UK Industry Growth
Sustainable Finance and Ethical Value Chains in 2026